





There was considerable opposition when the Government announced a few years ago that small firms should have to file their profit and loss accounts, and they had already relented to the extent that the filing requirement was to remain, but that Companies House would not publish the profit and loss accounts.
Today it has been announced that this controversial new reporting requirement has been dropped completely.
This is due to come in from 1 April 2028 and has now been placed indefinitely on hold.

WELCOME
Subtitle
Forward thinking accountancy services in West Sussex
Subtitle
The Martlet Partnership is a Worthing-based accountancy firm dedicated to delivering high-quality, constructive advice paired with a personal, positive approach. We provide comprehensive support to businesses and individuals of all types.
How may we help you today?
Latest news from the Martlet Partnership
Subtitle
Should landlords hold rental property personally or through a limited company?
For many landlords, one of the biggest planning questions is whether a rental property should be owned in their own name or through a limited company. The right answer depends on a number of factors, including tax rates, mortgage costs, plans for future investment, and whether profits will be withdrawn or reinvested.
With frozen tax thresholds, continuing pressure from borrowing costs, and Making Tax Digital for Income Tax beginning to apply to higher-income landlords from April 2026, it is increasingly important to review the ownership structure before buying, selling, transferring or expanding a property portfolio.
Tax treatment of rental profits
Personal ownership
Where a property is owned personally, rental profits are taxed as part of the landlord’s income. This means profits are charged at the landlord’s marginal Income Tax rate, which may be 20%, 40% or 45% depending on their total taxable income. For individual landlords of residential property, relief for mortgage interest and certain other finance costs is restricted. Rather than deducting these costs in full when calculating taxable rental profit, relief is generally given by way of a basic-rate tax reduction. This can be particularly unfavourable for higher-rate and additional-rate taxpayers, as they may be taxed on profits before finance costs have been fully relieved.
Limited company ownership
A limited company is a separate legal entity. The company owns the property, receives the rental income and pays Corporation Tax on its taxable profits. For some landlords, particularly those already paying higher rates of Income Tax, this can produce a more favourable annual tax position.
One of the key attractions of company ownership is that mortgage interest is normally deductible in full when calculating company profits. Corporation Tax is then charged on the remaining profit, currently at rates between 19% and 25%, depending on the level of taxable profits.
When a company structure may be useful
Holding property through a company may be worth considering where a landlord:
• is a higher-rate or additional-rate taxpaye;
• intends to build a larger property portfolio;
• wants to retain and reinvest profits rather than withdraw them each year;
• has significant mortgage interest costs; or
• wants more flexibility over timing and method of profit extraction.
A group structure, such as a holding company with subsidiary property companies, may also be appropriate for some investors. Depending on the circumstances, a group structure can provide greater flexibility over how funds are retained and reinvested within the group, although the tax position, additional administration, professional costs and compliance requirements need to be considered carefully.
Accessing rental profits
The way profits are accessed is a major difference between the two structures. If a property is owned personally, the position is relatively simple: once tax has been paid, the remaining profit belongs to the individual landlord.
By contrast, profits made by a limited company belong to the company. If the shareholder or director wants to take money out personally, further tax may arise. Extraction is commonly made through dividends, salary, interest on director’s loans, pension contributions, or a combination of these methods.
This means company ownership is usually most effective where profits can remain in the company and be used for future purchases, debt reduction, or wider investment planning, rather than being fully withdrawn every year for personal spending.
Selling the property and Capital Gains Tax
Personal ownership
Where an individual sells a residential rental property at a gain, Capital Gains Tax may be due. Residential property gains are currently taxed at 18% for basic-rate taxpayers and 24% for higher-rate and additional-rate taxpayers. The gain must normally be reported to HMRC, and any tax paid, within 60 days of completion.
Limited company ownership
If a company sells a property, any gain is generally subject to Corporation Tax rather than Capital Gains Tax. This may be beneficial in some cases, but the overall position must also consider how sale proceeds will be extracted from the company.
Transferring an existing property into a company
Landlords should take particular care before transferring a property they already own into a limited company. For tax purposes, the transfer is usually treated as taking place at market value, even if the company is owned by the same person and no money changes hands.
This can create immediate tax costs, including:
• Capital Gains Tax for the individual on any increase in value;
• Stamp Duty Land Tax for the company, usually based on market value;
• legal, valuation, mortgage and professional fees; and
• possible refinancing costs if existing personal borrowing has to be replaced with company borrowing.
Because of these upfront costs, incorporation is rarely neutral. It should be modelled carefully to establish whether any future tax savings justify the immediate tax and administrative burden.
What about existing landlords?
Do not assume that because company ownership would be preferable for a new purchase, an existing personally owned portfolio should automatically be transferred into a company. The tax and refinancing costs of incorporation can fundamentally change the calculation.
Other points to consider
The decision is not purely about annual tax. Landlords should also consider Inheritance Tax planning, Making Tax Digital obligations, borrowing terms, lender requirements, administrative costs, accounting responsibilities and long-term exit plans.
The SDLT position should also be considered before purchasing. The rates and reliefs applicable to residential investment property can materially affect the initial cost of an acquisition, particularly where a company is involved.
For new purchases, the ownership structure should ideally be considered before contracts are exchanged. Restructuring later can be expensive, so early advice can prevent unnecessary tax charges and help ensure the structure supports the landlord’s wider commercial objectives.
Hw we can help
There is no single answer that works for every landlord. The best structure depends on the landlord’s income position, borrowing levels, investment strategy, family circumstances and plans for using or reinvesting profits.
At The Martlet Partnership, we can model the tax consequences of personal and company ownership using your expected rental income, borrowing costs, other income and longer-term plans. This can be particularly valuable before a property is purchased or transferred, when there is still an opportunity to choose the most appropriate structure.
If you are considering buying a rental property or reviewing an existing portfolio, please speak to us before making any changes.
Posted 23/10/26
-
Good news for small businesses
The Government have now completely back downed on the requirement for small businesses to file their profit and loss accounts with Companies House.
23/10/26
-
HMRC VAT penalties: What businesses need to know.
HMRC’s VAT penalty regime has changed significantly from the previous default surcharge system. The current rules separate late submission, late payment and interest charges, meaning a business can face different consequences depending on whether it files late, pays late, or both.
22/10/26Overview of the current rules
The regime is intended to be more proportionate than the old system. Occasional mistakes are treated differently from repeated non-compliance, but businesses that regularly miss deadlines can still build up penalties quickly. The rules apply to VAT accounting periods starting on or after 1 January 2023, and interest is charged separately from penalties.
In broad terms, HMRC now uses a points-based system for late VAT returns and a time-based percentage penalty for late VAT payments. This means filing obligations and payment obligations need to be monitored separatly.
Late submission penalties
For late VAT returns, HMRC awards one penalty point for each missed submission deadline. A financial penalty is not charged immediately; it is triggered only when the business reaches the relevant points threshold. Once that threshold is met, HMRC issues a £200 penalty, and each further late return can lead to another £200 penalty while the business remains at or above the threshold.
Submission frequency &
Penalty threshold
Annual - 2 points
Quarterly - 4 points
Monthly - 5 points
Example: quarterly VAT returns
A business filing quarterly VAT returns would reach the penalty threshold after four late submissions. For example, if one return is late, the business receives one point. If later quarterly returns are also late and the total reaches four points, HMRC can issue a £200 penalty. Further late returns may then result in additional £200 penalties.
A key difference from the old default surcharge regime is that the late submission penalty is fixed. It does not depend on the amount of VAT due, so a penalty can still arise where the return is nil or shows a repayment due.
How penalty points can be removed
Penalty points can be reset, but the requirements depend on whether the business has already reached the penalty threshold. If the threshold has been reached, the business must submit all outstanding returns for the previous 24 months and complete a period of full compliance.
The required compliance period depends on how often returns are submitted:
Submission frequency & Compliance period required
Annual - 24 months
Quarterly - 12 months
Monthly - 6 months
If the penalty threshold has not been reached, individual points normally expire after 24 months.
Late payment penalties
Late payment penalties are based on how long the VAT remains unpaid. The sooner the liability is paid, or the sooner a Time to Pay arrangement is agreed with HMRC, the lower the penalty outcome is likely to be.
If the VAT is paid or a payment plan is agreed within the first 15 days after the due date, no late payment penalty is charged. From day 16, penalties begin to apply, and from day 31 a second daily penalty can also accrue until the balance is paid or an arrangement is in place.
Interest on late payments and repayments
Interest is separate from penalties. HMRC charges late payment interest from the first day the VAT is overdue until the amount is paid in full. The rate is linked to the Bank of England base rate plus 4%. Repayment interest may also be paid by HMRC where VAT is due back to the taxpayer, replacing the previous repayment supplement system.
Practical steps for businesses
The best way to avoid penalties is to have reliable systems for preparing VAT returns, checking filing deadlines and arranging payment in advance. Businesses should submit returns on time even where they cannot pay the VAT immediately, as late submission and late payment are penalised separately.
Where cash flow is under pressure, early contact with HMRC is important. A Time to Pay arrangement may reduce or prevent late payment penalties, although interest will normally continue to run on the outstanding balance until the VAT is fully settled.
This article is intended as general guidance only and is based on the rules in force at the date of publication. It does not constitute tax or professional advice. You should obtain advice appropriate to your particular circumstances before taking, or refraining from taking, any action.
-
New Recycling Rules Are Coming for Small Businesses - Are You Ready?
From 31 March 2027, new recycling requirements will apply to businesses and organisations with 10 full-time equivalent employees or fewer.
17/10/26These changes will require recyclable materials and food waste to be separated from general waste, and it's important that affected businesses understand their responsibilities ahead of the deadline.
To support businesses, The Sussex Chamber of Commerce is hosting a free webinar where they will explain what the new requirements mean, who they apply to, and the practical actions you can take now to prepare and remain compliant.
Who Should Attend?
This webinar is particularly relevant for:
• Sole traders
• Micro businesses
• Businesses with 10 full-time equivalent employees or fewer
• Small employers and business owners
• Retail, hospitality, charity, and service-sector organisations
• Anyone responsible for facilities, operations, or compliance within a small business
In This Session, They'll Cover:
• What the new Simpler Recycling requirements mean for your business
• Which waste streams need to be separated
• How to stay compliant and avoid potential penalties
• Practical, cost-effective ways to prepare ahead of the deadline
• Where to access further support and guidance
They'll also be inviting attendees to participate in a short breakout discussion and survey. This is an opportunity to share your experiences, ask questions, and help them better understand the challenges businesses may face as they prepare for the changes.
-
Business Industrial Competitiveness Scheme
Applications for this scheme open on 1 October but there is a short window only to 30 November, and if you do qualify, potential savings appear to be substantial.
1/10/26We appreciate that not that many of you will necessarily be eligible for this scheme, but we believe it is important that as many people as possible should be made aware of it because Government initiatives come and go, and do not necessarily seem to be widely publicised.
Applications for this scheme open on 1 October but there is a short window only to 30 November, and if you do qualify, potential savings appear to be substantial.
If you think this is relevant to you, please do not hesitate to contact us and if you need help with the application, we will be pleased to put you in touch with one of our UK200 Group Prime Partners.
Who could qualify?
A business must:
Be registered at Companies House with a relevant eligible SIC code
Operate within an eligible manufacturing sector
Manufacture an eligible product in Great Britain
Use at least 33 MWh of grid supplied electricity annually at the relevant manufacturing site
The electricity threshold is perhaps lower than many businesses might expect. 33,000 kWh a year does not necessarily mean a large factory or a particularly energy-intensive business. A relatively small manufacturing workshop running machinery, compressors, extraction and other production equipment could potentially exceed that level.
In practical terms, BICS is most worth looking at for manufacturers with meaningful electricity usage whose products fall within the Government's eligible manufacturing categories. The greater the electricity consumption and the proportion of the site dedicated to eligible manufacturing, the greater the potential benefit.
The products themselves are particularly important. The eligible list covers goods produced across the Government's manufacturing frontier and foundational industries.
This includes areas such as aerospace, automotive, batteries, clean energy, defence and digital technologies, but also much more traditional manufacturing. Metals and metal products, chemicals, glass and ceramics, paper and packaging, machinery and industrial equipment, electrical components and a wide range of other manufactured goods can potentially fall within the eligible product categories.
It is therefore worth looking beyond the SIC code alone and considering what the business actually manufactures. SIC codes can sometimes be historic or may no longer accurately reflect a company's current activities, so in some cases they may need to be updated to properly reflect what the business does.
How much support is available?
BICS does not provide an exemption from the entire electricity bill. Instead, eligible businesses receive an exemption from certain policy costs included within their electricity charges, covering the Renewables Obligation, Feed-in Tariff and Capacity Market.
The level of exemption depends on how much of the electricity used at each manufacturing site relates to eligible production:
25% or less attributable to eligible manufacturing – no exemption
More than 25% but below 50% – 50% exemption from these policy costs
50% or more – 100% exemption from these policy costs
At the highest level of support, Government estimates the BICS exemptions could reduce a manufacturer's overall electricity bill by up to 25%, with the exemptions worth approximately £35 to £40 per MWh.
To put that into context, a manufacturer consuming 2,000 MWh annually at the 100% exemption level could potentially receive annualised support of around £70,000 to £80,000 once all of the relevant BICS exemptions are fully in effect.
The first application window is particularly important
The application window is fairly short, it opens on 1 October and closes on 30 November 2026.
Businesses entering the scheme could also receive an additional payment in 2027, calculated by reference to the support they would have received had BICS been operating from April 2026.
There is another reason to look at eligibility early. Once a BICS application has been submitted, it cannot be amended, so it is important to get the eligibility position, product classifications, electricity calculations and supporting evidence right first time.
-
Companies House reforms from April 2028
The Government has now confirmed significant changes to Companies House filing requirements, taking effect from 1 April 2028.
15/06/2026While these reforms represent a major shift for many small businesses, clients of The Martlet Partnership are already well positioned, as we have long managed digital filing and full compliance on their behalf.
WHAT IS CHANGING?
• More detailed accounts will be filed
Small companies and micro-entities will be required to file a profit and loss account alongside the balance sheet.
• Your sensitive information can remain private
Following strong opposition from the business community — a campaign we were proud to support — companies will be able to opt out of publishing their profit and loss account on the public register. This is a significant and welcome outcome, preserving confidentiality while still meeting regulatory requirements.
• Abridged accounts will be removed
The option to file abridged accounts will be abolished, moving all companies towards a more standardised format.
• Digital filing becomes mandatory for everyone
All companies will need to file accounts using approved software. This is already how we operate, so our clients will not need to change their processes.
WHAT THIS MEANS IN PRACTICE
For many businesses, these changes will involve new systems, new processes and additional complexity. However, for clients of The Martlet Partnership:
There is no change to how your accounts are currently filed.
You are already compliant with digital filing requirements.
We will ensure you meet the updated disclosure rules without additional burden.
The main practical change will be that more financial information is submitted to Companies House — but with continued control over what is made public.
HOW WE WILL SUPPORT YOU
At The Martlet Partnership, our role is to make these changes straightforward and stress-free:
We will continue to handle all filings on your behalf, as we do now.
We will ensure full compliance with the new requirements.
We will advise on the opt-out of profit and loss publication, where appropriate.
We will keep you informed with clear, practical guidance.
We will deal with the detail, so you can focus on running your business.
OUR VIEW
We welcome the Government’s decision to allow businesses to keep profit and loss accounts off the public register, helping to protect commercially sensitive information. We are proud to have supported the wider professional and business community in pushing for this outcome.
LOOKING AHEAD
The rules do not take effect until April 2028, and most of the groundwork is already in place for our clients. For you, this is not a disruption — it is simply a continuation of the robust, compliant approach we already take on your behalf.
If you would like to discuss how these changes affect your business, please do get in touch.
-
Tax free mileage rate increase
It is nice to be able to share some good news for a change! Yesterday, The Chancellor announced that the tax free mileage rate that can be paid to employees or claimed by self-employed people, will increase from 45p to 55p for the first 10,000 business miles in a tax year.
26/05/2026
This is the first increase since April 2011, and is massively overdue, but nonetheless has now finally been dealt with by the Government.
As a reminder, 55p per mile is the maximum that can be paid for the first 10,000 miles of business mileage to employees who use their own vehicle, be it a car or van, in connection with their employment or claimed by self-employed people. It is a not a requirement to pay the 55p, and if mileage payments are made to employees in a lesser amount, they can claim tax relief on the difference.
The 25p per mile over 10,000 miles remains unchanged, as does the motorbike rate.
There are a number of targeted measures in yesterday’s announcement, one of the headline announcements being a cut in the VAT rate on children’s meals from 20% to 5% across the summer holiday. It will be interesting to see how many businesses show a notable increase in the number of children’s meals served during this period!
If you have any queries relating to how to claim the business mileage rate, please do not hesitate to contact us.
-
Tax Facts 2026 - 2027
We have pleasure in attaching our annual tax card containing at-a-glance summary of all tax and allowances applicable in the forthcoming tax year.
05/2026
-
New Statutory Sick Pay legislation
Business owners can be forgiven if they feel they have been under attack from a slew of new regulations, none of which appear to be for the benefit of business itself.
06/05/2026If you are a sole trader, there is the joy of MTD to subscribe to, meaning that instead of doing one tax return a year, you will now do five.
For company owners, there has been the deep joy of having to obtain a Personal Identification Code, without which you can no longer file documents for your company, and which Companies House have been relentlessly pursuing, whilst making it as difficult and awkward as possible for people to obtain in many cases.
From the start of the new tax year, there is then new legislation relating to Statutory Sick Pay, which means that employees are now entitled to Statutory Sick Pay from day one of absence. This will mean that even if a member of staff is off sick for just one day, that person will have to be paid and you cannot recover the SSP from the Government.
All employers need to be aware of this because if you fail to pay a member of staff who if off sick, then it is very likely they will know their own rights!
Attached is a document with some details analysis of how the impact of this legislation will affect employers.
-
Business Confidence Survey
We are conducting a short survey to understand the current business sentiment, including their outlook for the future. The timing of this survey has been coordinated to capture your thoughts given the November 2025 budget and the geopolitical landscape.
26/01/2026Nevertheless, there will be a 2% increase to dividend tax which effectively means that business owners who keep their income below the higher rate of tax have seen an increase in their effective tax rates, when taking their companies and their dividends combined, from 26% three years ago to 36% plus next year.
We will be looking at strategies of how to extract profits from companies which once again will need to be revised for the 26/27 tax year in due course.
There are also likely to be changes to private landlords’ strategy in relation to residential property, either by an increase in rent to reflect the additional tax or perhaps an increase in the use of small companies to shelter residential portfolios.
There is a lot of small detail to digest within the full analysis and we have not had time to assimilate all of it yet but, if you have any queries as to how changes in legislation might affect you, please do not hesitate to contact us.
We conduct this business confidence survey from time to time to understand confidence levels and the views of businesses on their outlook. The findings provide us with insights to develop appropriate support for businesses and individuals.
We are conducting this survey in collaboration with other members firms of the UK200Group, the UK’s leading professional organisation of chartered accountants and law firms, of which we are a member.
This means we will capture feedback from businesses from right across the UK which we can use to help develop and shape support to help businesses like yours.
The survey will only take 1-2 minutes of your time to participate. It contains just 4 short questions.
Please take a moment to participate by clicking the link below.

For more information or to discuss your requirements call +44 (0)1903 600555 or use the contact form below.
Subtitle

The Martlet Partnership LLP
Martlet House, E1 Yeoman Gate, Yeoman Way, Worthing, West Sussex BN13 3QZ
Tel.: +44 (0)1903 600555
Martlet House, E1 Yeoman Gate, Yeoman Way, Worthing, West Sussex BN13 3QZ
Tel.: +44 (0)1903 600555
CONTACT US


WELCOME
Subtitle
Forward thinking accountancy services in West Sussex.
Subtitle
The Martlet Partnership is a Worthing-based accountancy firm dedicated to delivering high-quality, constructive advice paired with a personal, positive approach. We provide comprehensive support to businesses and individuals of all types.
Latest news from the Martlet Partnership
Subtitle
Should landlords hold rental property personally or through a limited company?
For many landlords, one of the biggest planning questions is whether a rental property should be owned in their own name or through a limited company.
The right answer depends on a number of factors, including tax rates, mortgage costs, plans for future investment, and whether profits will be withdrawn or reinvested.
With frozen tax thresholds, continuing pressure from borrowing costs, and Making Tax Digital for Income Tax beginning to apply to higher-income landlords from April 2026, it is increasingly important to review the ownership structure before buying, selling, transferring or expanding a property portfolio.
Tax treatment of rental profits
Personal ownership
Where a property is owned personally, rental profits are taxed as part of the landlord’s income. This means profits are charged at the landlord’s marginal Income Tax rate, which may be 20%, 40% or 45% depending on their total taxable income. For individual landlords of residential property, relief for mortgage interest and certain other finance costs is restricted. Rather than deducting these costs in full when calculating taxable rental profit, relief is generally given by way of a basic-rate tax reduction. This can be particularly unfavourable for higher-rate and additional-rate taxpayers, as they may be taxed on profits before finance costs have been fully relieved.
Limited company ownership
A limited company is a separate legal entity. The company owns the property, receives the rental income and pays Corporation Tax on its taxable profits. For some landlords, particularly those already paying higher rates of Income Tax, this can produce a more favourable annual tax position.
One of the key attractions of company ownership is that mortgage interest is normally deductible in full when calculating company profits. Corporation Tax is then charged on the remaining profit, currently at rates between 19% and 25%, depending on the level of taxable profits.
When a company structure may be useful
Holding property through a company may be worth considering where a landlord:
• is a higher-rate or additional-rate taxpaye;
• intends to build a larger property portfolio;
• wants to retain and reinvest profits rather than withdraw them each year;
• has significant mortgage interest costs; or
• wants more flexibility over timing and method of profit extraction.
A group structure, such as a holding company with subsidiary property companies, may also be appropriate for some investors. Depending on the circumstances, a group structure can provide greater flexibility over how funds are retained and reinvested within the group, although the tax position, additional administration, professional costs and compliance requirements need to be considered carefully.
Accessing rental profits
The way profits are accessed is a major difference between the two structures. If a property is owned personally, the position is relatively simple: once tax has been paid, the remaining profit belongs to the individual landlord.
By contrast, profits made by a limited company belong to the company. If the shareholder or director wants to take money out personally, further tax may arise. Extraction is commonly made through dividends, salary, interest on director’s loans, pension contributions, or a combination of these methods.
This means company ownership is usually most effective where profits can remain in the company and be used for future purchases, debt reduction, or wider investment planning, rather than being fully withdrawn every year for personal spending.
Selling the property and Capital Gains Tax
Personal ownership
Where an individual sells a residential rental property at a gain, Capital Gains Tax may be due. Residential property gains are currently taxed at 18% for basic-rate taxpayers and 24% for higher-rate and additional-rate taxpayers. The gain must normally be reported to HMRC, and any tax paid, within 60 days of completion.
Limited company ownership
If a company sells a property, any gain is generally subject to Corporation Tax rather than Capital Gains Tax. This may be beneficial in some cases, but the overall position must also consider how sale proceeds will be extracted from the company.
Transferring an existing property into a company
Landlords should take particular care before transferring a property they already own into a limited company. For tax purposes, the transfer is usually treated as taking place at market value, even if the company is owned by the same person and no money changes hands.
This can create immediate tax costs, including:
• Capital Gains Tax for the individual on any increase in value;
• Stamp Duty Land Tax for the company, usually based on market value;
• legal, valuation, mortgage and professional fees; and
• possible refinancing costs if existing personal borrowing has to be replaced with company borrowing.
Because of these upfront costs, incorporation is rarely neutral. It should be modelled carefully to establish whether any future tax savings justify the immediate tax and administrative burden.
What about existing landlords?
Do not assume that because company ownership would be preferable for a new purchase, an existing personally owned portfolio should automatically be transferred into a company. The tax and refinancing costs of incorporation can fundamentally change the calculation.
Other points to consider
The decision is not purely about annual tax. Landlords should also consider Inheritance Tax planning, Making Tax Digital obligations, borrowing terms, lender requirements, administrative costs, accounting responsibilities and long-term exit plans.
The SDLT position should also be considered before purchasing. The rates and reliefs applicable to residential investment property can materially affect the initial cost of an acquisition, particularly where a company is involved.
For new purchases, the ownership structure should ideally be considered before contracts are exchanged. Restructuring later can be expensive, so early advice can prevent unnecessary tax charges and help ensure the structure supports the landlord’s wider commercial objectives.
Hw we can help
There is no single answer that works for every landlord. The best structure depends on the landlord’s income position, borrowing levels, investment strategy, family circumstances and plans for using or reinvesting profits.
At The Martlet Partnership, we can model the tax consequences of personal and company ownership using your expected rental income, borrowing costs, other income and longer-term plans. This can be particularly valuable before a property is purchased or transferred, when there is still an opportunity to choose the most appropriate structure.
If you are considering buying a rental property or reviewing an existing portfolio, please speak to us before making any changes.
Posted 23/10/26
-
Good news for small businesses
The Government have now completely back downed on the requirement for small businesses to file their profit and loss accounts with Companies House.
23/10/26There was considerable opposition when the Government announced a few years ago that small firms should have to file their profit and loss accounts, and they had already relented to the extent that the filing requirement was to remain, but that Companies House would not publish the profit and loss accounts.
Today it has been announced that this controversial new reporting requirement has been dropped completely.
This is due to come in from 1 April 2028 and has now been placed indefinitely on hold.
-
New Recycling Rules Are Coming for Small Businesses - Are You Ready?
From 31 March 2027, new recycling requirements will apply to businesses and organisations with 10 full-time equivalent employees or fewer.
22/10/26These changes will require recyclable materials and food waste to be separated from general waste, and it's important that affected businesses understand their responsibilities ahead of the deadline.
To support businesses, The Sussex Chamber of Commerce is hosting a free webinar where they will explain what the new requirements mean, who they apply to, and the practical actions you can take now to prepare and remain compliant.
Who Should Attend?
This webinar is particularly relevant for:
• Sole traders
• Micro businesses
• Businesses with 10 full-time equivalent employees or fewer
• Small employers and business owners
• Retail, hospitality, charity, and service-sector organisations
• Anyone responsible for facilities, operations, or compliance within a small business
In This Session, They'll Cover:
• What the new Simpler Recycling requirements mean for your business
• Which waste streams need to be separated
• How to stay compliant and avoid potential penalties
• Practical, cost-effective ways to prepare ahead of the deadline
• Where to access further support and guidance
They'll also be inviting attendees to participate in a short breakout discussion and survey. This is an opportunity to share your experiences, ask questions, and help them better understand the challenges businesses may face as they prepare for the changes.
-
Companies House reforms from April 2028
While these reforms represent a major shift for many small businesses, clients of The Martlet Partnership are already well positioned, as we have long managed digital filing and full compliance on their behalf.
05/2026WHAT IS CHANGING?
• More detailed accounts will be filed
Small companies and micro-entities will be required to file a profit and loss account alongside the balance sheet.
• Your sensitive information can remain private
Following strong opposition from the business community — a campaign we were proud to support — companies will be able to opt out of publishing their profit and loss account on the public register. This is a significant and welcome outcome, preserving confidentiality while still meeting regulatory requirements.
• Abridged accounts will be removed
The option to file abridged accounts will be abolished, moving all companies towards a more standardised format.
• Digital filing becomes mandatory for everyone
All companies will need to file accounts using approved software. This is already how we operate, so our clients will not need to change their processes.
WHAT THIS MEANS IN PRACTICE
For many businesses, these changes will involve new systems, new processes and additional complexity. However, for clients of The Martlet Partnership:
There is no change to how your accounts are currently filed.
You are already compliant with digital filing requirements.
We will ensure you meet the updated disclosure rules without additional burden.
The main practical change will be that more financial information is submitted to Companies House — but with continued control over what is made public.
HOW WE WILL SUPPORT YOU
At The Martlet Partnership, our role is to make these changes straightforward and stress-free:
We will continue to handle all filings on your behalf, as we do now.
We will ensure full compliance with the new requirements.
We will advise on the opt-out of profit and loss publication, where appropriate.
We will keep you informed with clear, practical guidance.
We will deal with the detail, so you can focus on running your business.
OUR VIEW
We welcome the Government’s decision to allow businesses to keep profit and loss accounts off the public register, helping to protect commercially sensitive information. We are proud to have supported the wider professional and business community in pushing for this outcome.
LOOKING AHEAD
The rules do not take effect until April 2028, and most of the groundwork is already in place for our clients. For you, this is not a disruption — it is simply a continuation of the robust, compliant approach we already take on your behalf.
If you would like to discuss how these changes affect your business, please do get in touch.
-
Tax free mileage rate increase
It is nice to be able to share some good news for a change! Yesterday, The Chancellor announced that the tax free mileage rate that can be paid to employees or claimed by self-employed people, will increase from 45p to 55p for the first 10,000 business miles in a tax year.
05/2026
This is the first increase since April 2011, and is massively overdue, but nonetheless has now finally been dealt with by the Government.
As a reminder, 55p per mile is the maximum that can be paid for the first 10,000 miles of business mileage to employees who use their own vehicle, be it a car or van, in connection with their employment or claimed by self-employed people. It is a not a requirement to pay the 55p, and if mileage payments are made to employees in a lesser amount, they can claim tax relief on the difference.
The 25p per mile over 10,000 miles remains unchanged, as does the motorbike rate.
There are a number of targeted measures in yesterday’s announcement, one of the headline announcements being a cut in the VAT rate on children’s meals from 20% to 5% across the summer holiday. It will be interesting to see how many businesses show a notable increase in the number of children’s meals served during this period!
If you have any queries relating to how to claim the business mileage rate, please do not hesitate to contact us.
-
Business Industrial Competitiveness Scheme
Applications for this scheme open on 1 October but there is a short window only to 30 November, and if you do qualify, potential savings appear to be substantial.
1/10/26We appreciate that not that many of you will necessarily be eligible for this scheme, but we believe it is important that as many people as possible should be made aware of it because Government initiatives come and go, and do not necessarily seem to be widely publicised.
Applications for this scheme open on 1 October but there is a short window only to 30 November, and if you do qualify, potential savings appear to be substantial.
If you think this is relevant to you, please do not hesitate to contact us and if you need help with the application, we will be pleased to put you in touch with one of our UK200 Group Prime Partners.
Who could qualify?
A business must:
Be registered at Companies House with a relevant eligible SIC code
Operate within an eligible manufacturing sector
Manufacture an eligible product in Great Britain
Use at least 33 MWh of grid supplied electricity annually at the relevant manufacturing site
The electricity threshold is perhaps lower than many businesses might expect. 33,000 kWh a year does not necessarily mean a large factory or a particularly energy-intensive business. A relatively small manufacturing workshop running machinery, compressors, extraction and other production equipment could potentially exceed that level.
In practical terms, BICS is most worth looking at for manufacturers with meaningful electricity usage whose products fall within the Government's eligible manufacturing categories. The greater the electricity consumption and the proportion of the site dedicated to eligible manufacturing, the greater the potential benefit.
The products themselves are particularly important. The eligible list covers goods produced across the Government's manufacturing frontier and foundational industries.
This includes areas such as aerospace, automotive, batteries, clean energy, defence and digital technologies, but also much more traditional manufacturing. Metals and metal products, chemicals, glass and ceramics, paper and packaging, machinery and industrial equipment, electrical components and a wide range of other manufactured goods can potentially fall within the eligible product categories.
It is therefore worth looking beyond the SIC code alone and considering what the business actually manufactures. SIC codes can sometimes be historic or may no longer accurately reflect a company's current activities, so in some cases they may need to be updated to properly reflect what the business does.
How much support is available?
BICS does not provide an exemption from the entire electricity bill. Instead, eligible businesses receive an exemption from certain policy costs included within their electricity charges, covering the Renewables Obligation, Feed-in Tariff and Capacity Market.
The level of exemption depends on how much of the electricity used at each manufacturing site relates to eligible production:
25% or less attributable to eligible manufacturing – no exemption
More than 25% but below 50% – 50% exemption from these policy costs
50% or more – 100% exemption from these policy costs
At the highest level of support, Government estimates the BICS exemptions could reduce a manufacturer's overall electricity bill by up to 25%, with the exemptions worth approximately £35 to £40 per MWh.
To put that into context, a manufacturer consuming 2,000 MWh annually at the 100% exemption level could potentially receive annualised support of around £70,000 to £80,000 once all of the relevant BICS exemptions are fully in effect.
The first application window is particularly important
The application window is fairly short, it opens on 1 October and closes on 30 November 2026.
Businesses entering the scheme could also receive an additional payment in 2027, calculated by reference to the support they would have received had BICS been operating from April 2026.
There is another reason to look at eligibility early. Once a BICS application has been submitted, it cannot be amended, so it is important to get the eligibility position, product classifications, electricity calculations and supporting evidence right first time.
-
Companies House reforms from April 2028
While these reforms represent a major shift for many small businesses, clients of The Martlet Partnership are already well positioned, as we have long managed digital filing and full compliance on their behalf.
05/2026WHAT IS CHANGING?
• More detailed accounts will be filed
Small companies and micro-entities will be required to file a profit and loss account alongside the balance sheet.
• Your sensitive information can remain private
Following strong opposition from the business community — a campaign we were proud to support — companies will be able to opt out of publishing their profit and loss account on the public register. This is a significant and welcome outcome, preserving confidentiality while still meeting regulatory requirements.
• Abridged accounts will be removed
The option to file abridged accounts will be abolished, moving all companies towards a more standardised format.
• Digital filing becomes mandatory for everyone
All companies will need to file accounts using approved software. This is already how we operate, so our clients will not need to change their processes.
WHAT THIS MEANS IN PRACTICE
For many businesses, these changes will involve new systems, new processes and additional complexity. However, for clients of The Martlet Partnership:
There is no change to how your accounts are currently filed.
You are already compliant with digital filing requirements.
We will ensure you meet the updated disclosure rules without additional burden.
The main practical change will be that more financial information is submitted to Companies House — but with continued control over what is made public.
HOW WE WILL SUPPORT YOU
At The Martlet Partnership, our role is to make these changes straightforward and stress-free:
We will continue to handle all filings on your behalf, as we do now.
We will ensure full compliance with the new requirements.
We will advise on the opt-out of profit and loss publication, where appropriate.
We will keep you informed with clear, practical guidance.
We will deal with the detail, so you can focus on running your business.
OUR VIEW
We welcome the Government’s decision to allow businesses to keep profit and loss accounts off the public register, helping to protect commercially sensitive information. We are proud to have supported the wider professional and business community in pushing for this outcome.
LOOKING AHEAD
The rules do not take effect until April 2028, and most of the groundwork is already in place for our clients. For you, this is not a disruption — it is simply a continuation of the robust, compliant approach we already take on your behalf.
If you would like to discuss how these changes affect your business, please do get in touch.
-
Tax free mileage rate increase
It is nice to be able to share some good news for a change! Yesterday, The Chancellor announced that the tax free mileage rate that can be paid to employees or claimed by self-employed people, will increase from 45p to 55p for the first 10,000 business miles in a tax year.
05/2026
This is the first increase since April 2011, and is massively overdue, but nonetheless has now finally been dealt with by the Government.
As a reminder, 55p per mile is the maximum that can be paid for the first 10,000 miles of business mileage to employees who use their own vehicle, be it a car or van, in connection with their employment or claimed by self-employed people. It is a not a requirement to pay the 55p, and if mileage payments are made to employees in a lesser amount, they can claim tax relief on the difference.
The 25p per mile over 10,000 miles remains unchanged, as does the motorbike rate.
There are a number of targeted measures in yesterday’s announcement, one of the headline announcements being a cut in the VAT rate on children’s meals from 20% to 5% across the summer holiday. It will be interesting to see how many businesses show a notable increase in the number of children’s meals served during this period!
If you have any queries relating to how to claim the business mileage rate, please do not hesitate to contact us.
-
Tax Facts 2026 - 2027
We have pleasure in attaching our annual tax card containing at-a-glance summary of all tax and allowances applicable in the forthcoming tax year.
05/2026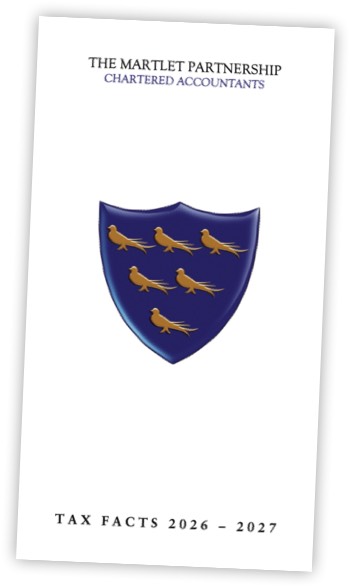
-
New Statutory Sick Pay legislation
Business owners can be forgiven if they feel they have been under attack from a slew of new regulations, none of which appear to be for the benefit of business itself.
06/05/2026If you are a sole trader, there is the joy of MTD to subscribe to, meaning that instead of doing one tax return a year, you will now do five.
For company owners, there has been the deep joy of having to obtain a Personal Identification Code, without which you can no longer file documents for your company, and which Companies House have been relentlessly pursuing, whilst making it as difficult and awkward as possible for people to obtain in many cases.
From the start of the new tax year, there is then new legislation relating to Statutory Sick Pay, which means that employees are now entitled to Statutory Sick Pay from day one of absence. This will mean that even if a member of staff is off sick for just one day, that person will have to be paid and you cannot recover the SSP from the Government.
All employers need to be aware of this because if you fail to pay a member of staff who if off sick, then it is very likely they will know their own rights!
Attached is a document with some details analysis of how the impact of this legislation will affect employers.
-
Business Confidence Survey
We are conducting a short survey to understand the current business sentiment, including their outlook for the future. The timing of this survey has been coordinated to capture your thoughts given the November 2025 budget and the geopolitical landscape.
26/01/2026Nevertheless, there will be a 2% increase to dividend tax which effectively means that business owners who keep their income below the higher rate of tax have seen an increase in their effective tax rates, when taking their companies and their dividends combined, from 26% three years ago to 36% plus next year.
We will be looking at strategies of how to extract profits from companies which once again will need to be revised for the 26/27 tax year in due course.
There are also likely to be changes to private landlords’ strategy in relation to residential property, either by an increase in rent to reflect the additional tax or perhaps an increase in the use of small companies to shelter residential portfolios.
There is a lot of small detail to digest within the full analysis and we have not had time to assimilate all of it yet but, if you have any queries as to how changes in legislation might affect you, please do not hesitate to contact us.
We conduct this business confidence survey from time to time to understand confidence levels and the views of businesses on their outlook. The findings provide us with insights to develop appropriate support for businesses and individuals.
We are conducting this survey in collaboration with other members firms of the UK200Group, the UK’s leading professional organisation of chartered accountants and law firms, of which we are a member.
This means we will capture feedback from businesses from right across the UK which we can use to help develop and shape support to help businesses like yours.
The survey will only take 1-2 minutes of your time to participate. It contains just 4 short questions.
Please take a moment to participate by clicking the link below.
How may we help you today?




For more information or to discuss your requirements call us now on +44 (0)1903 600555 or use the contact form below.
Subtitle